Financial advice for life's big decisions
Whether you’re leaving the Australian Defence Force, are a Veteran with a Permanent Impairment or SRDP offer, planning your retirement, have been offered a voluntary redundancy, navigating a defined benefit pension, or building long-term wealth … we help you make informed financial decisions with confidence.
What can we help you with today?
Considering Transition
Thinking about your future options and what life outside the ADF looks like.
Planning for ADF transitionPreparing to Transition
You're planning to leave the ADF and want to understand your finances, super, entitlements and what comes next.
Planning for ADF transitionVeteran with PI or SRDP offer
You've had a medical discharge, and have now received a DVA Permanent Impairment or SRDP offer.
Advice on PI and SRDP offersGovernment Employee
You work in a government department with PSS or CSS Super
Advice on PSS and CSS superPre-Retirement
Establishing a new routine, housing, community connections, and family stability.
Guide to retirement planningRetirement
Maximising your superannuation and preparing for a comfortable post-work lifestyle.
Retiring on $1 millionPreparing to Transition from the Army, Air Force or Navy?
Leaving Defence within the next 12 months?
Learn about your super, DVA entitlements, leave, housing and the financial decisions that matter before your discharge.
Received a Permanent Impairment offer from the DVA?
Understand how your PI compensation works, your payment options, taxation, investment considerations and the long-term financial decisions that can help protect your future.
Considering a Special Rate Disability Pension (SRDP)?
Learn how SRDP works, compare your options, understand the long-term financial implications and make an informed decision before accepting your offer.
TESTIMONIALS
Our customer reviews
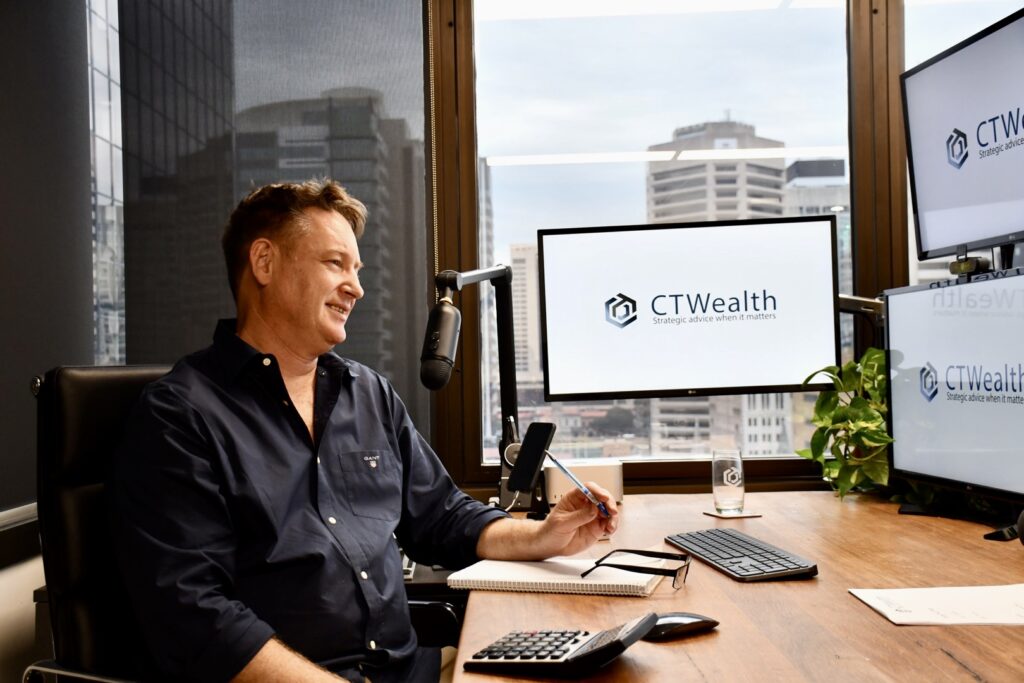
About Cameron Teague
Cameron Teague is a Certified Financial Planner (CFP)® who holds a bachelor’s degree and postgraduate qualifications in financial planning.
He has been working as a financial planner since 2001 having commenced at Whitaker McNaught and then traversing across both private practice and Industry Funds.
His Industry Fund experience began in 2006 and has continued through in his current private practice.
Cameron has extensive experience in providing complex financial strategies combining best-in-practice products across both Industry Fund and retail product environments to deliver the best outcomes for clients.
Genuine & transparent fee for service
My practice operates under a genuine and transparent fee for service model.
I do not charge asset-based fees and I do not accept any form of commission.
There are no hidden ongoing fees.
I have operated under a fee-for-service model since 2002 and was an early adaptor of this approach at a time that the majority of financial planners relied on product linked commission payment structures. My early adoption of fee-for-service reflected the beliefs I developed early on in my career around the need for fee transparency and importantly, the need for the separation of advice fees and product.
This approach to fees has been fundamental in ensuring that advice I have provided throughout my career has always been in the best interests of my clients.
This thinking extends to the fee approach taken at Cameron Teague Wealth Advisory. Once we identify your precise advice needs I will be able to provide you with a cost for advice which will cover the provision of the initial strategy solutions. Implementation costs are optional and quoted separately.
After the initial provision of advice, I offer a number of fee-based options for staying on track, including pay-as-you-go meetings, annual review meetings and an ongoing service model.
I do not charge fixed ongoing advice fees based on the amount you have invested. This is quite unique and is an important point of differentiation.
Often advice relationships are structured around the provision of initial advice for a fee, but then the agreement of an ongoing relationship. This used to be called a trail commission and is now often called an “Asset Based Fee”. It was these fees that led to the “fees for no service” issues that were so strongly called out in the recent Hayne Royal Commission.
Best practice referral partners
Rather than trying to be all things to all people, my practice will focus on my strength which is developing & delivering complex financial strategies.
Where other professional services are required, I will refer you to the best-in-practice for those areas.
I have established preferred partners for this purpose including estate planning, broking & accountancy.
I do not have any financial arrangements for referrals with any professionals. You will simply be referred to the best person for your needs.
Privately owned with no connection to product providers
My practice is privately owned and operated (not by a bank or other product provider).
It is not vertically integrated and we have no sales targets.
We do not accept any ‘soft dollar’ incentives from product providers.
This approach means we can give our clients access to best-in-practice products across both the retail and Industry Fund environments.
Recommendations are based on your needs, goals and objectives rather than a need to sell products.